
As AI capabilities become commonplace, InsurTech providers must distinguish themselves through focused problems, explainable decisions and demonstrable business value.
As AI capabilities become commonplace, InsurTech providers must distinguish themselves through focused problems, explainable decisions and demonstrable business value.
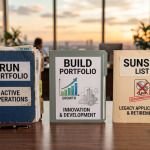
Separating run and build portfolios, modeling future costs and identifying systems for retirement can strengthen the business case for insurance technology investment.
AI regulation is evolving, but carriers can act now to control sensitive data, preserve human accountability and avoid costly retrofits.
AI can accelerate software development, but insurers still need rigorous governance, cost controls and technical disciplines to turn speed into lasting value.
Automated employment and income data can help life insurers reduce applicant friction while improving underwriting speed, consistency and confidence.
Claims modernization depends on secure, verifiable vehicle data that helps carriers improve payment accuracy, fraud detection, auditability and customer experience.

Carriers can gain more from AI by moving decision support upstream before low-fit submissions consume underwriting capacity.
Money movement affects claims experience, partner ecosystems and operational efficiency, making payments infrastructure a foundation for insurance modernization.
As AI automates routine work, insurers should redeploy capacity toward service, resilience, product innovation and workforce development.
As insurers move from AI pilots to agentic systems, trusted operational data will determine whether automation improves decisions or amplifies risk.