
(Image source: IIR.)
We live in an era of significant generational, operational and technological change. The useful life of everything new seems shorter than it once was, even as emerging capabilities continue to impress consumers. Yet not everything old is positioned for mass extinction. Properly cared for, technologies that are a generation or more old can remain useful for a surprisingly long time. Managing this bifurcation in technology environments is one of the more significant challenges facing IT organizations and their leaders today.
Just because you can replace something doesn’t mean you should. And while AI can produce impressive outcomes, it is not a cure-all, despite the hype. In some cases, it can create bigger problems than the ones it solves. The challenge is to use new and emerging technology in the right way, to solve the right problems.
Customer engagement and experience development offer an instructive use case. Recently, while trying to expand coverage with a Tier 1 P&C carrier, I was confounded by its AI-driven interface. My questions were complicated, and the desired coverages spanned multiple products. The experience had been designed for a simple use case. As I later discovered, the only way to talk to a human was to say, “I want to lapse these policies.” Like magic, the experience changed. Too late. By then, I really did want to lapse them, having found a regional carrier that was more than happy to talk with me.
In addition to complexity, generational differences in communication styles and language are very real. Boomers and Zoomers can use the same words to mean different things, different words to mean the same thing and experience products differently. Some banks are effective at recognizing this. Insurance carriers, however, can be tempted to find the one right answer and double down on it. That creates real risk: A one-size-fits-all solution can become one size fits none.
This raises the question of what insurers measure to assess business outcomes. In the P&C carrier example, the company may have been winning on cost and human call-handling time. If customer retention was the goal, however, the experience was an epic failure. The carrier lost the existing business and the opportunity to sell something new.
That brings us to mass customization—or, in the customer-experience context, mass personalization. AI creates an opportunity for insurers to deliver more varied and responsive experiences at scale. But realizing that opportunity requires more than placing an AI-driven interface between the customer and the carrier. If insurers want to compete in an era of heightened competition and product commoditization, they will need to use data, customer-behavior insights and emerging technologies—including AI—to tailor experiences while preserving access to human expertise when customers need it.
Standardization and Customization are not Opposites
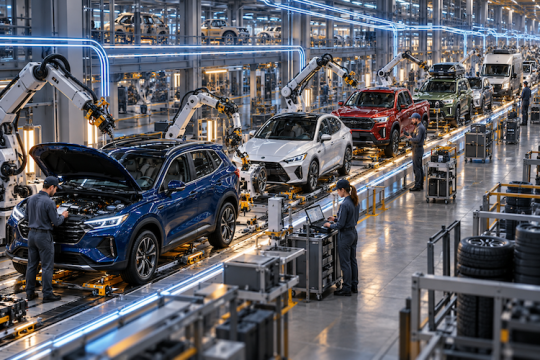
Sometimes, stepping outside our industry can also be insightful. Banks have a more granular understanding of individual customers because of their transaction volumes, but even cohort-level insights can be invaluable. A less obvious example can be found in a modern automobile plant, which might best be described as industrial choreography. A recent tour of BMW’s plant in South Carolina showed how a complex ecosystem of people, processes, suppliers and customer preferences can support a highly automated yet stunningly effective business model. Standardization and customization are not opposites: The right operating model can accommodate considerable variation without sacrificing scale or efficiency.
There is no doubt that this is an exciting time for insurance. That said, given the industry’s complexity and long liability tails, multidimensional execution will be required to produce winning outcomes. AI may expand what is possible, but it does not relieve insurers of the need to understand their customers, design for different circumstances or choose metrics that reflect business value. Burning large piles of money to build solutions that do not address real business needs, while ignoring existing problems, will never be the right answer—despite what it says in the airline magazine.